Cash Gab with Noah - August 2026
Noah Ross - Aug 01, 2026
In this issue, we’ll be covering investment concentration risk, buying a home in the GTA, along with some relevant current events.
Quick Nugget of the Day
Why Doing Nothing is Sometimes the Best Investment Decision
A famous investing anecdote comes from a Fidelity analysis done in 2014 that reportedly found a consistent theme across the best-performing accounts… they had either passed away or forgotten about their account. The common denominator was simple, they weren’t trading. They simply stayed invested.
While the story has taken on a life of its own over the years, the lesson aligns with what we know about investor behaviour. Many investors hurt their long-term returns by buying when optimism is high and selling when fear takes over. Greed and fear are powerful forces, and investors who achieve the best outcomes over time are often those who minimize their influence.
Of course, this doesn't mean you should ignore your portfolio. What you're invested in matters. A diversified portfolio of quality businesses is very different from a concentrated position in a single stock. The lesson isn't to stop paying attention to what you’re invested in, it's to avoid constantly reacting.
The message here is simple, long-term investing rewards patience more than prediction. Assuming you have a diversified portfolio of good investments, the less often you change horses, the more likely you are to reach your destination.
The Great Financial Squeeze: Navigating the Early Mortgage & Family Years
For many people in their 30s looking to have families, the goal isn’t maximizing retirement savings. It’s staying afloat, avoiding financial stress, and making it through one of life’s most expensive chapters.
The Financial Pressure That Needs to Be Talked About
There’s a period of life that often arrives all at once for many: you get married, buy a home, get a pet, and start thinking about kids or already have them. Suddenly, your financial picture changes dramatically.
The mortgage payment is higher than your old rent and property taxes show up. Your furnace breaks or your roof needs attention. Daycare costs start appearing on the horizon and sleep becomes more scarce with your spare time quickly disappearing. Exciting, right?!
At the same time, household income may temporarily decline because parental leaves. For many families, this isn’t just a period of higher expenses. It’s a period where many of life’s major transitions happen within a five-to-seven-year window. And if you’re living in a high-cost area like the Greater Toronto Area, the numbers can feel overwhelming.
The anxiety I hear from friends, colleagues, and clients in this stage isn’t:
“Will I be able to comfortably retire at 65?”
It’s:
“How do I financially survive the next few years without losing my sanity?”
The Challenge Isn’t One Expense. It’s All of Them Together.
Individually, homeownership costs can be manageable. So can childcare costs and a temporary reduction in income during a parental leave. Wedding events, travel, and social commitments are doable. The problem is that they often arrive simultaneously.
While you’re adjusting to mortgage payments and home maintenance costs, friends may be planning destination weddings, bachelor and bachelorette parties, engagement celebrations, and other events that carry both financial and social pressure.
You want to be present for the people you care about but every new obligation competes with your growing list of responsibilities at home.
This results in a constant feeling of tradeoffs.
Buy the Home You Can Afford After Kids Arrive
One of the biggest mistakes I see is evaluating affordability based on today’s lifestyle. If your plan is to have children in the next few years, the home purchase should be evaluated with that reality already built into the projections. Before buying, ask yourself:
- What will daycare cost?
- What will parental leave do to household income and what happens if one spouse reduces working hours?
- How much additional spending will come with raising children?
If a house only works financially before children arrive, it may not actually be affordable for the lifestyle you’re planning. Building that buffer in advance can help avoid significant and expensive stress later.
Protect the Plan, Not Just the Income
As financial obligations grow, risk management becomes increasingly important. It’s not uncommon for young families to neglect planning for the impact of an unexpected health event. Consider whether your family would be financially secure if:
- One spouse passed away prematurely
- One spouse became disabled and couldn’t work
- A major illness interrupted earning power
This is where tools such as term life insurance, disability insurance, and critical illness insurance can play an important role. When mortgages, children, and long-term financial commitments enter the picture, protecting against catastrophe becomes just as important as building wealth.
Plan for Parental Leave Before It Arrives
Parental leave is one of the biggest predictable financial changes many families will experience. The key word is predictable. Rather than waiting until income drops, run the numbers early (whether that’s when the baby is on the way or earlier). You should understand what your household income will look like, what expenses will increase, and how much cash flow you may need to replace.
For households that are aggressive savers, the answer may simply be temporary adjustments like reducing contributions to investment accounts. It can also mean scaling back travel and spending less on discretionary purchases.
These are not financial failures but are rather intentional short-term tradeoffs during a unique stage of life. If savings need to reduce or pause for a year or two while your family is growing, that’s reasonable.
Keep the Compounding Engine Running
While saving may become more difficult during these years, try to avoid stopping entirely. One of the most powerful forces in wealth creation is simply allowing investments to compound over long periods of time. Even modest balances left untouched can quietly grow in the background while life is happening. The goal during these years doesn’t have to be maximizing investment contributions every year. Sometimes the goal is simply preserving momentum.
Build a Larger Emergency Fund Than You Think You Need
Life becomes less predictable when you own a home and have children. Appliances break, roofs leak, vehicles need repairs, and job changes happen. This is why I often encourage young families to think about their emergency fund as another form of insurance. In this stage in life, I generally suggest rounding up for the amount to keep.
You Can Increase Your Pay Too
Most of what we’ve discussed so far is around spending consciousness. But that’s only half of the equation. The other half is increasing what comes into the household. While this is a time of life where expenses go up, it is also a point where careers have been established and opportunities to increase your compensation can be more available.
Career advancement, professional development, side income opportunities, business ownership, and strategic job changes can all improve cash flow. Cost management creates breathing room, but income growth creates options. Both are powerful.
Give Yourself Permission to Be in a Different Season of Life
The early mortgage and family years are often not the years of maximum savings. They’re the years of building a home, raising children, managing responsibility, and creating stability. Success should simply mean:
- Paying the bills comfortably and maintaining financial security
- Protecting your family and preserving peace of mind
- And most importantly, enjoying the ride
These years are about successfully navigating one of the busiest and most meaningful chapters of life.
Closing Thoughts
Having recently gotten married, my wife Cassy and I are thinking about many of these same questions ourselves. Through conversations with friends, colleagues, and clients, I’ve realized that many people are experiencing concerns when it comes to these transitions.
The good news is that these challenges become much easier to manage when you can see the numbers clearly.
With a few assumptions, some thoughtful planning, and the right tools, it's possible to stress test different scenarios and build a roadmap for the years ahead.
If you're navigating your own early mortgage and family years and would like to explore your situation in more detail, I'd be happy to have a conversation. One of my goals is to help make this stage feel more achievable and less overwhelming, so families can focus on enjoying this stage of life instead of worrying about it.
In the News
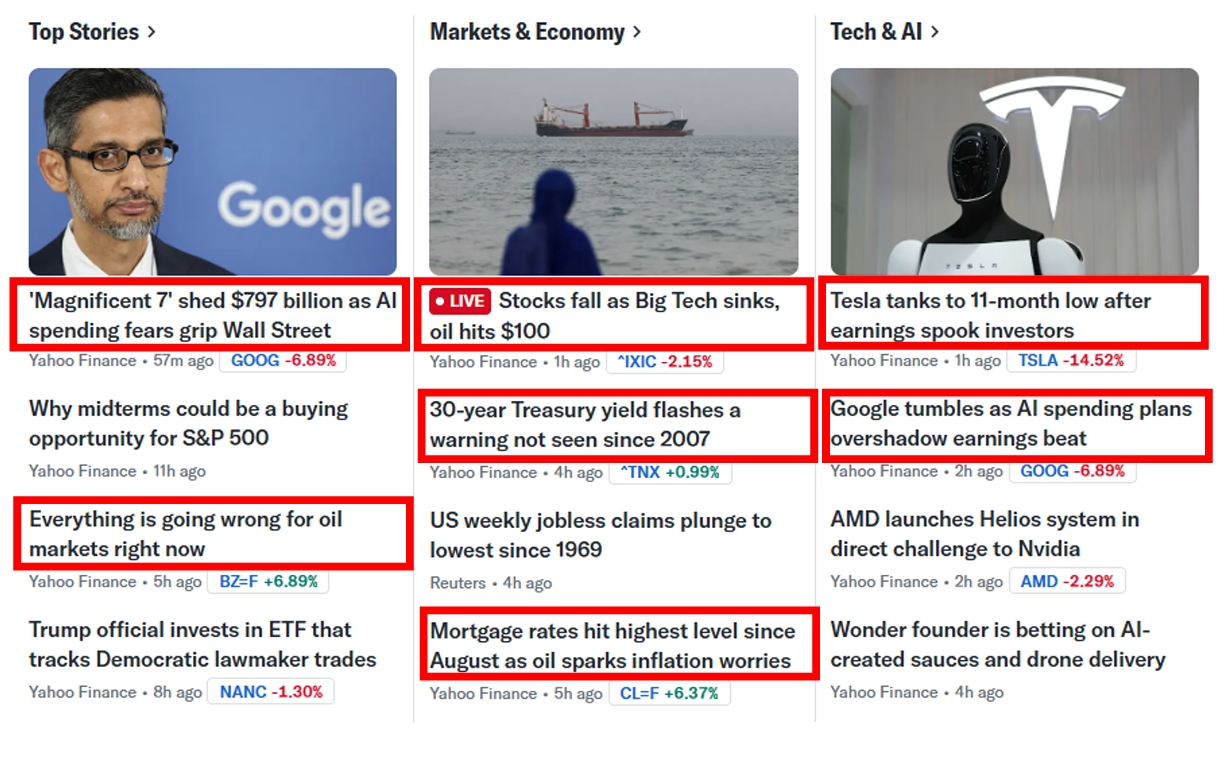
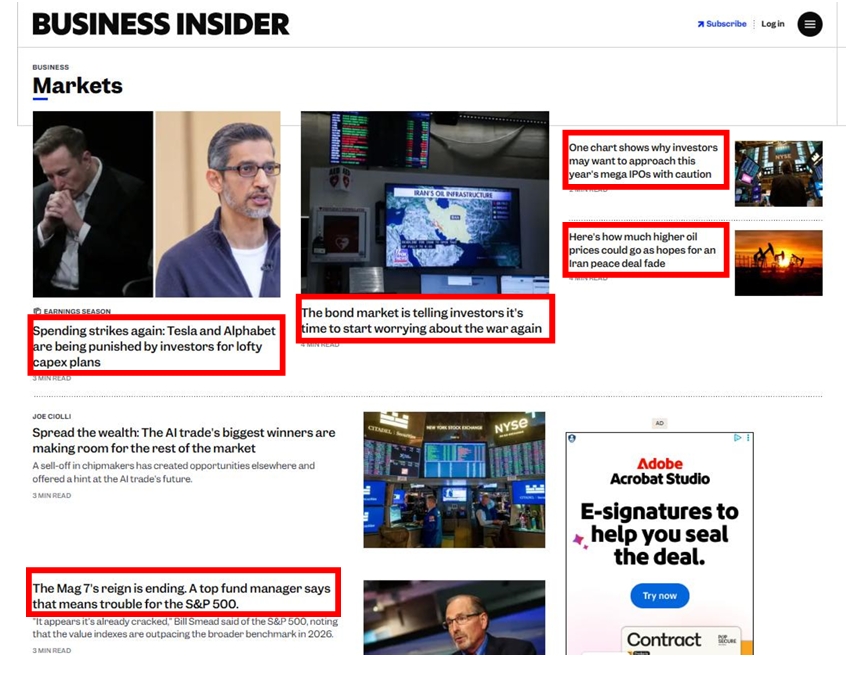
On the topic of today's nugget about staying the course, I looked at the home pages of Yahoo Finance and Business Insider on July 23, 2026, and highlighted the negative headlines in red. There's a lot of red.
The purpose of this exercise isn't to ignore the news. Staying informed is important. Rather, it's a reminder that extreme negative or positive headlines often dominate our attention and can influence how we feel about our investments.
There will always be reasons to be concerned about the future. Successful investing isn't about ignoring those concerns. It's about acknowledging them without letting them derail a long-term plan.
Nothing profound here, just an interesting observation.
July 23, 2026 Yahoo Finance Homepage – Yahoo Finance
July 23, 2026 Business Insider Homepage – Business Insider
The Ross Group: Who We Are
At Ross Group Wealth Advisors, we work with future-minded investors to keep them on track toward greater wealth. Through our unique approach to portfolio management and wealth planning, we deliver smart risk and tax strategies and guide sound decisions that secure their wealth and expand their lives.
What We Provide
We act as your financial quarterback, building comprehensive, long-term strategies, not quick fixes. Our wealth plans aim to minimize taxes and safeguard your financial health today and for the future.
We proactively review your portfolio and overall financial picture, update your wealth plan regularly, and ensure you stay aligned with your goals. We engage with your priorities, uncover opportunities, and challenge assumptions about what you can do and when.
Community Engagement
Join the wait list for an in-person Cash Gab Session:
What is a Cash Gab Session?
Cash Gab brings together peers in similar careers and life stages to share, listen, and learn about financial topics that matter to you. The goal is to build a community of like-minded, future-oriented people aiming to achieve financial freedom.