Investment Insights Autumn 2026
Paul D'Elia - Oct 01, 2026
- Estate Planning
- Financial Planning
- Investment Services
- Portfolio Management
- Retirement
- Special Reports and Newsletters
- Tax Planning
- Total Client Experience
- Wealth Management
• Back to School: Estate Planning & the RESP • Benefit From Your Losses & Gains • Six Ways to Minimize Taxes on Your Estate • Equity Market Rotation: Is Boring Back? • The Productivity Paradox: Artificial Intelligence
An Economic & Market Bird’s-Eye View
Canada’s brief “technical recession” made headlines over the summer, raising an interesting question: Whatever happened to the recession?
Over the past 17 years, Canada has experienced just one recession — a brief, two-month downturn brought on by the pandemic. This contrasts with much of the post-war period, when recessions occurred more frequently. What has changed?
Of course, policymakers have been quicker to respond when disruptions occur. That said, the economy itself has also evolved: it is larger, more diversified and increasingly dominated by services and technology, as businesses have become more efficient and adaptable.
A similar pattern can be seen in financial markets. Bear markets certainly haven’t disappeared, but recent downturns have often been relatively short-lived, with recoveries occurring at remarkable speed. This prompts a broader question: Are prolonged downturns becoming a thing of the past? While many would caution against such a conclusion, it may point to something more fundamental: economic and market cycles themselves are evolving. One place to look is how the investing landscape itself has changed. Information now travels globally in seconds. Faster information flows, trading automation and lower transaction costs have contributed to greater market activity. In the early 1980s, around 100 million shares traded daily on the New York Stock Exchange; by 2020, this had risen to over one billion.1
Participation has also become democratized. Building a diversified portfolio once required meaningful capital. Today, low-cost investment products and internet access have lowered barriers to entry. In 1983, only 13 percent of Canadians reported owning equities, but this has grown to over 50 percent.2 These structural changes have also reshaped how investors participate. The average holding period for a stock, once spanning eight years, is now measured in months.1
Market structure has also shifted. The number of U.S.-listed companies has halved from about 8,000 in 1997 to 4,000 today.3 Yet global market capitalization has expanded from about $50 trillion in 2011 to over $140 trillion today.4 Meanwhile, the range of investment products has expanded significantly, providing investors with more ways to diversify and deploy capital. And there is plenty of capital available. U.S. capital on the sidelines has doubled from pandemic levels to around $8 trillion.5
Taken together, these shifts raise key questions: How should markets behave in an environment defined by faster information flows, lower barriers to entry, broader investor participation and more capital on the sidelines, yet fewer public companies in which to deploy it? Do these changes imply a structural shift in market behaviour? Are today’s valuations a reflection of these forces in action? Could sharper but shorter bursts of volatility and rapid narrative reversals become more common? Perhaps the anatomy of future bull and bear markets will differ from those of the past.
Yet, amid all this change, some things have remained remarkably consistent. A $100,000 investment in the S&P/TSX Composite Index 30 years ago, with reinvested dividends, would have grown to over $1.5 million today.* Markets may evolve and narratives may shift, but their capacity to create wealth over time has endured. In many ways, perhaps there has never been a better time to be an investor.
*With reinvested dividends, S&P/TSX Composite Index TR 9,944.05 on 7/31/96; 151,469.31 on 7/31/26.
- www.visualcapitalist.com/thedecline-of-long-term-investing/;
- www.cbc.ca/news/business/survey-says-almost-half-of-canadian-adults-own-stocks-1.208778;
- https://data.worldbank.org/indicator/CM.MKT.LDOM.NO?locations=US;
- https://en.wikipedia.org/wiki/Market_capitalization;
- Money market funds: www.apolloacademy.com/understanding-demand-for-treasuries-and-why-the-yield-curve-is-steepening/
Back to School: Estate Planning & the RESP
While many use the RESP to support family education and create a lasting legacy, it’s often overlooked in estate planning.
With kids back to school, it’s a timely reminder of the Registered Education Savings Plan (RESP) benefits:
- Income-splitting — When RESP funds are withdrawn for qualified educational purposes, accumulated earnings (and grants) are typically taxed in the hands of the beneficiary, often in a lower tax bracket.
- Tax-deferred growth — Investments within the RESP grow taxsheltered until withdrawal.
- Government grants — The Canada Education Savings Grant (CESG) provides up to $7,200 in matching grants per beneficiary.
Yet, these benefits can be lost if the RESP is not addressed in an estate plan. Why? The RESP belongs to the subscriber, the person who sets it up and contributes to it, and not the beneficiary. Many investors assume it works like a Registered Retirement Savings Plan (RRSP), which passes directly to a named beneficiary and bypasses probate at death. However, RESP assets do not transfer in the same way. Generally, the RESP forms part of the estate immediately upon the subscriber’s death. If there is no joint subscriber or no successor subscriber named in the Will, it is typically collapsed. As assets fall into the deceased subscriber’s estate, it can trigger:
- Tax on accumulated income payments, payable by the estate;
- Repayment of CESGs; and
- Probate fees, if applicable, with assets subject to creditor claims.
As a result, the RESP loses its benefits. It may also disrupt legacy plans if estate beneficiaries are different from the RESP beneficiary.
To protect the intent of the RESP:
1. Name a joint subscriber (for spouses/partners or former spouses who are the legal parent of the beneficiary only). The joint subscriber can continue managing the plan.
2. Appoint a successor subscriber in your Will. A trusted individual can take over the plan. Keep in mind that the new subscriber would control the plan and could potentially collapse it.
3. Consider a testamentary trust. Under certain conditions, a Will can name a trust as successor subscriber, allowing contributions to continue beyond death (subject to contribution limits). By addressing the RESP in your estate planning, you can safeguard its benefits and ensure your legacy supports the intended student(s).
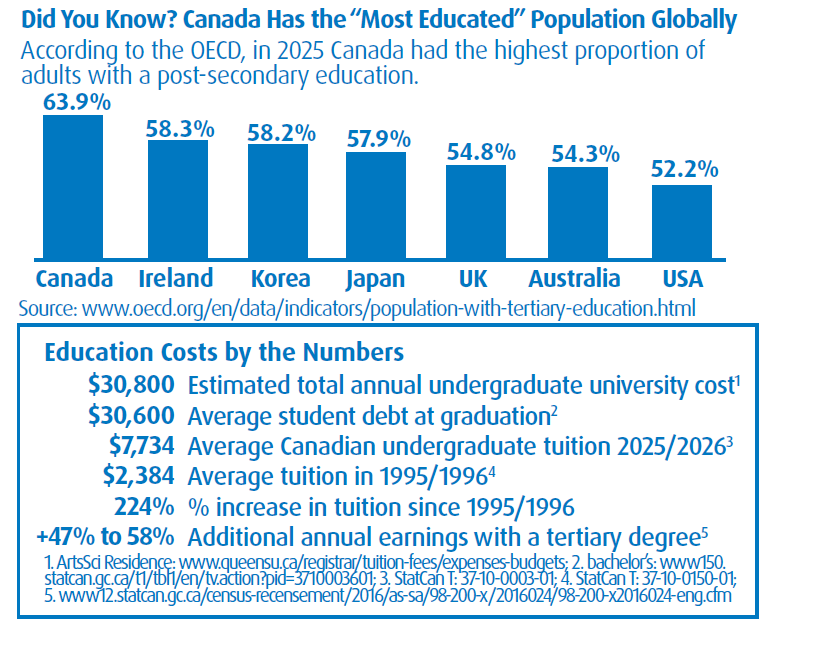
Year-End Tax Planning: Benefit From Your Losses & Gains
Don’t look now, but the final months of the year are quickly approaching. There may be actions to take to help improve your 2026 tax position or enhance the tax-efficiency of your financial plan.
If you are thinking of making portfolio adjustments, there may be a way to gain from your losses — or further benefit from your gains:
Gain From Your Losses Through Tax-Loss Harvesting — Generally, an investment held in a non-registered account that is sold for less than its original cost will result in a capital loss. For tax purposes, the capital loss can be used to offset taxable capital gains realized during the year to reduce your current tax liability. If you don’t have sufficient taxable capital gains to offset the loss, the net capital loss can be carried back to any of the previous three taxation years to offset realized capital gains, or carried forward to use against future realized capital gains.
Benefit From Your Gains: Donating Securities In-Kind — Donating publicly-traded securities “in-kind” that have appreciated in value may eliminate the tax liability on the capital gain triggered and allow for a donation tax credit for the fair market value of the securities. Do not sell are the legal parent of the beneficiary only). The joint subscriber can continue managing the plan. 2. Appoint a successor subscriber in your Will. A trusted individual can take over the plan. Keep in mind that the new subscriber would control the plan and could potentially collapse it. 3. Consider a testamentary trust. Under certain conditions, a Will can name a trust as successor subscriber, allowing contributions to continue beyond death (subject to contribution limits). By addressing the RESP in your estate planning, you can safeguard its benefits and ensure your legacy supports the intended student(s). securities and donate the proceeds, as part of the tax benefit will be lost. If securities have declined in value, simply sell them to claim the capital loss and donate cash to receive a donation tax credit. If you’re subject to the alternative minimum tax, be aware that there may be tax implications. Remember to make charitable donations well in advance of the December 31, 2026, deadline to count towards your 2026 taxes.
Here are a handful of other ideas to help improve your tax position:
- Split income. This may include electing to split eligible pension income with a spouse or paying reasonable salaries to family members for services provided to your self-employed business.
- Contribute to your RRSP. You still have 60 days after the calendar year end to make contributions for the 2026 tax year, but the earlier you contribute, the greater opportunity for tax-deferred growth.
- Plan for the pension income tax credit. If you’re age 65 or older and don’t have eligible pension income, consider opening a small Registered Retirement Income Fund (RRIF) or purchasing an annuity.
- Withdraw from the TFSA before year-end. If you plan to withdraw, consider doing so before year-end. Contribution room resets at the start of the calendar year, so withdrawals after December 31, 2026, won’t restore contribution room until January 1, 2028.
For more information or ideas, please contact the office.
Six Ways to Minimize Taxes on Your Estate
Planning ahead can help preserve more of your hard-earned wealth for your heirs, rather than the tax authorities.
As we approach the final months of the year, many focus on actions to reduce the current year’s tax bill. But it may also be an opportune time to consider how to manage future tax obligations. In Canada, unlike the U.S., there is no estate tax in the traditional sense. Instead, you’re deemed to have disposed of assets at fair market value at death, and your estate is subject to tax on accrued gains. For many estates, the greatest tax exposure comes from registered accounts, capital gains in non-registered accounts and appreciated assets like vacation properties. Here are six ways to help minimize taxes on your estate:
1. Defer Taxes — In some cases, the tax liability on appreciated assets can be so significant that estates are forced to liquidate assets, such as a business or family cottage. Deferring taxes can help avoid this. A spousal rollover allows assets to transfer to a surviving spouse or spousal trust, with associated tax liabilities generally deferred until the spouse dies or assets are sold. Tax-deferred rollovers may also be available in some circumstances for eligible beneficiaries, such as a financially dependent child or grandchild.
2. Use Exemptions — Tax exemptions can provide meaningful savings. For example, with the Principal Residence Exemption (PRE), if you own more than one property over time, careful planning around which property is designated as your principal residence, and for which years, can help reduce overall capital gains tax. With the Lifetime Capital Gains Exemption (LCGE), business owners may be able to shelter gains on qualified business shares or certain farm or fishing property.
3. Don’t Overlook Foreign Estate Taxes — If you own assets outside Canada, or if beneficiaries live in a country with an estate tax, there may be exposure to foreign taxes. Many Canadians own U.S. assets. U.S. “situs” property, which includes U.S. real estate and shares in U.S. corporations, may be subject to the U.S. estate tax. There are strategies to help minimize potential U.S. estate tax, but advanced planning is often necessary.
4. Freeze Taxes — Business owners may choose to freeze the value of their business for tax purposes today, while transferring future growth to the next generation. By using an estate freeze, you can continue to control the business and lock in your future tax obligations, while the other party benefits from any increases in the value of the business (but is also liable for future taxes on the growth).
5. Plan on Giving — Leaving a legacy through charitable donations can create a lasting impact while reducing taxes. Properly structured gifts can reduce tax in the year of death and the preceding year. In the year of death, the maximum donation amount increases to 100 percent of net income (up from the 75 percent limit in a normal year). Gifts made during your lifetime, such as to family members or charitable causes, can also reduce the size of your taxable estate while providing immediate benefits.
6. Use an RRSP/RRIF Drawdown Strategy — Registered retirement accounts can represent one of the largest tax liabilities at death. A proactive drawdown strategy may help reduce this exposure. Instead of withdrawing only the required minimum amounts, some choose to gradually withdraw additional funds during lower-income years, smoothing income over time and potentially paying tax at lower marginal rates. This can also allow assets to be reinvested in more tax-efficient vehicles, such as a TFSA, or support gifting strategies. Be aware that higher withdrawal amounts can have other consequences, such as potentially triggering the OAS clawback.
Equity Market Rotation: Is Boring Back?
Broader market leadership has been a notable theme in 2026.
After many years in which a handful of mega-cap tech companies drove significant market performance, there’s been a broader investment focus throughout 2026. One way to view this shift has been in the performance of the Dow Jones Industrial Average (DJIA), widely known as the “Dow.”
Earlier this year when the Dow surpassed the 50,000 mark, it prompted headlines such as: “The Dow, the Uncool Index, Has Its Moment in the Sun.”1 The milestone reflected renewed interest in many of the established, mature companies often viewed as less glamorous than their tech peers, as market leadership broadened beyond tech.
This year marks the Dow’s 130th anniversary. Created in 1896 by Charles Dow, then-editor of The Wall Street Journal, it originally tracked 12 major industrial firms, adopting the name “Industrial Average.” Today, the Dow tracks 30 leading companies and is updated periodically to reflect dominant sectors of the modern economy.
Unlike other indices, the Dow uses a “price-weighted” methodology. This is calculated by adding component share prices and dividing them by a divisor that accounts for stock splits or other structural changes. By contrast, indices such as the S&P/TSX Composite, S&P 500 and NASDAQ weight companies by market capitalization, or total value of outstanding shares.
Is the Dow still a useful index? A new generation of retail investors argues that “the index is about as relevant as paper stock certificates or ticker tape.” Critics have long suggested that a 30-company sample is too narrow to represent the broader market. Others point to its price-weighted structure, where higher-priced stocks have greater influence than lower-priced counterparts.
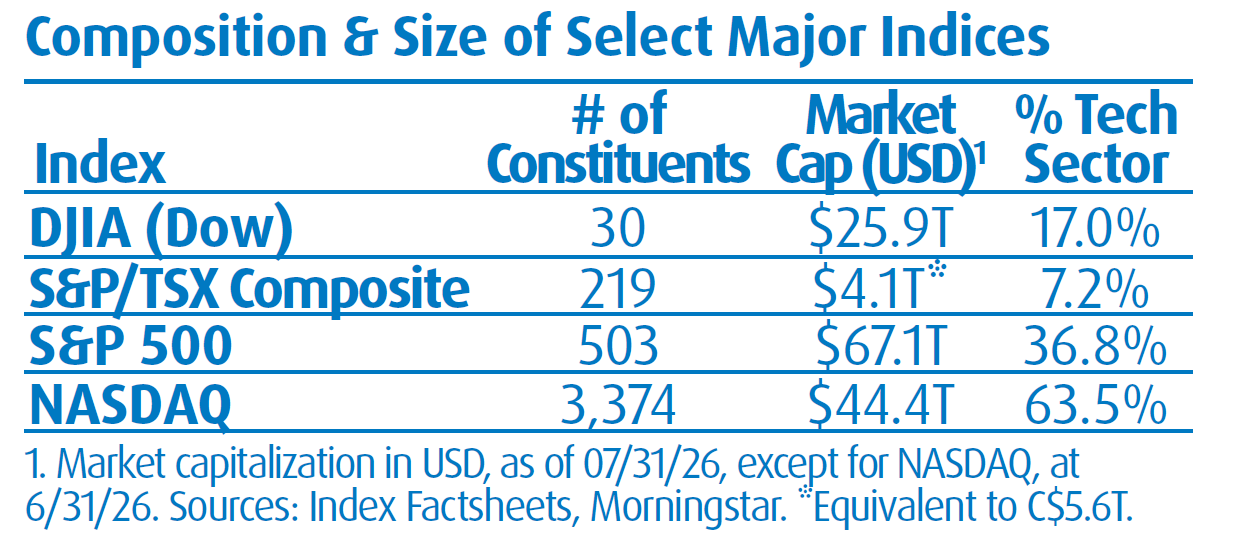
Yet the Dow still offers a useful perspective due to its broader sector representation. While technology continues to dominate the NASDAQ and remains a significant component of the S&P 500, it represents a much smaller share of the Dow.
Taking a broader perspective, no index is perfect, but each offers insight into distinct parts of the markets. The Dow’s long history and milestones serve as a reminder of the markets’ long-term trajectory of resilience and economic progress.
- Wall Street Journal, Markets
The Productivity Paradox of Artificial Intelligence
As artificial intelligence (AI) improves workplace productivity, a natural concern follows: If we can accomplish more with fewer resources, will we also need fewer workers? Productivity is a fundamental driver of long-term economic growth. When businesses can produce more with the same or fewer resources, this can support profitability, wages and living standards. At a time when Canada faces persistent productivity challenges, an aging population and slower labour-force growth, AI’s potential contribution shouldn’t be overlooked. Yet, will it lead to widespread job losses, or an “AI job-apocalypse”?
Consider the productivity gains already being observed. A recent Stanford University paper examined how large language model tools (generative AI systems known as LLMs) are improving a range of knowledgebased tasks. The results are striking. In every common work task studied, generative AI reduced completion time by at least half, and in most cases by around 70 to 75 percent. Adoption is also accelerating: LLM use among U.S. workers rose from 30.1 percent in December 2024 to 38.3 percent by December 2025.1
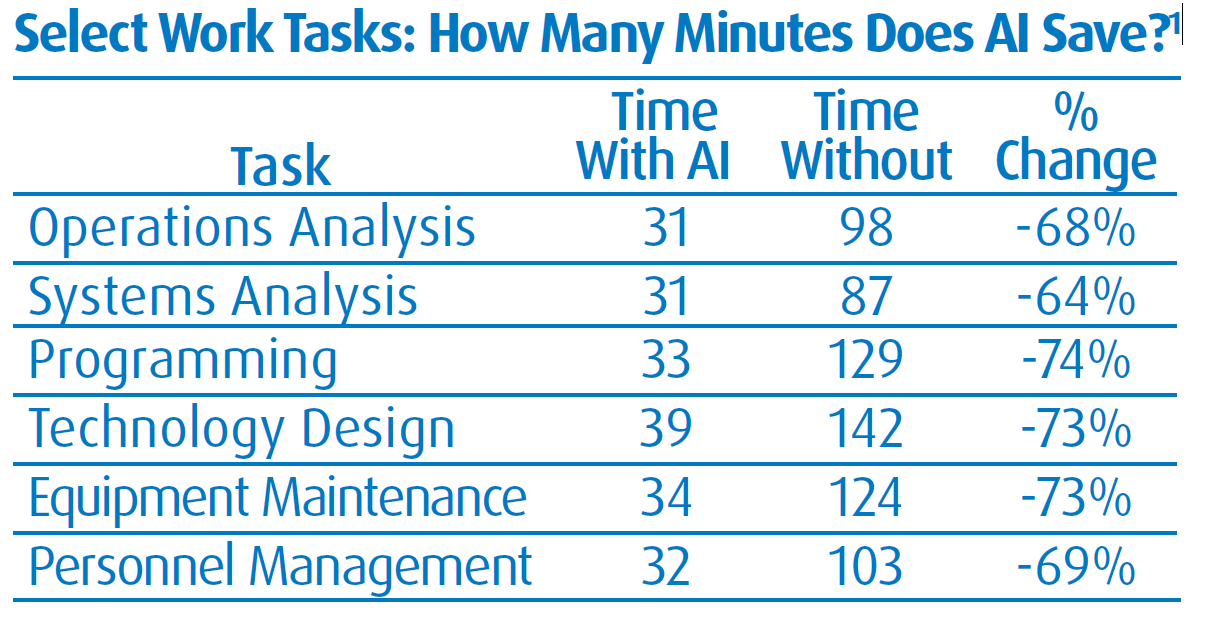
At first glance, the implications for employment may seem obvious. If workers can accomplish the same task in half the time, businesses should need fewer workers. And there is little doubt that AI will eliminate certain tasks, compress some roles and potentially displace workers along the way. There is evidence this may already be happening.2 But greater productivity does not necessarily mean fewer jobs. When technology allows businesses to produce more at a lower cost, prices can fall, demand can rise and entirely new uses can emerge. A related concept is the Jevons Paradox: greater efficiency can actually increase consumption rather than reduce it. William Jevons first observed the phenomenon in the 19th century, when improvements in the efficiency of coal use resulted in greater — not lower — coal consumption.
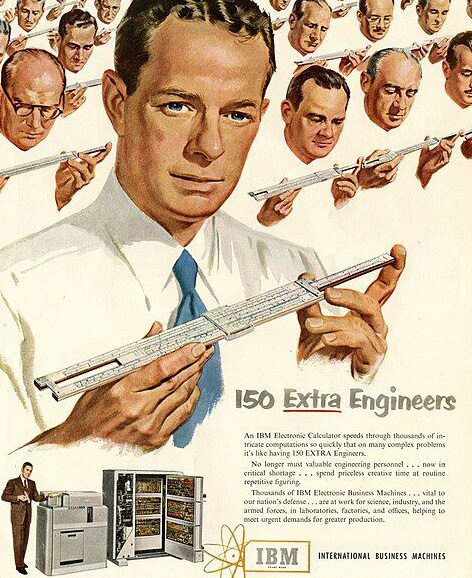
Labour markets have demonstrated a similar ability to adapt. In 1951, an IBM advertisement for its electronic calculator promoted it as capable of replacing 150 engineers. Yet 75 years later, engineers remain indispensable. Technology changed what engineers could accomplish and contributed to new industries requiring their skills. Similar predictions have accompanied countless technological advances.
Productivity also creates possibilities difficult to anticipate in advance. One study estimates that technology has facilitated the creation of new occupations that didn’t exist in 1940 and now employ roughly 60 percent of today’s workers.3 Many would have been unimaginable to previous generations.
This isn’t to dismiss the disruption ahead. AI will change the labour market, with some occupations more vulnerable than others. But productivity growth has historically been a key driver of economic progress, potentially supporting greater output, profitability, investment and ultimately new sources of demand. The question may not simply be how many jobs AI eliminates, but what greater productivity allows us to create.
- https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5136877;
- https://fortune.com/2026/04/06/ai-tech-displacement-effect-gen-z-16000- jobs-per-month/;
- https://www.gspublishing.com/content/research/en/reports/2023/03/27/d64e052b-0f6e-45d7-967b-d7be35fabd16.html
To Our Clients:
With trade tensions resurfacing toward
the end of the summer, we are reminded that
no bull market comes without its challenges.
Many economists estimate that the latest
tariff changes will subtract less than one
percentage point from GDP. While certain sectors
will be hit harder, we continue to look
beyond the oft-shifting headlines and adjust
as risks and opportunities evolve. Underlying
structural forces continue to support demand
in energy, commodities and infrastructure,
as well as for financially strong, globally
diversified businesses.
During the Thanksgiving season and beyond,
we are reminded of the many things to be
thankful for: we live in a nation of peace,
prosperity and resilience. Thank you for
entrusting us to steward your wealth.
D’Elia Wealth Advisory Group
BMO Nesbitt Burns
Paul D’Elia
B.Comm. (Hons), CIM®, PFP®, FCSI®
Senior Wealth Advisor
Senior Portfolio Manager
BMO Private Wealth is a brand name for a business group consisting of Bank of Montreal and certain of its affiliates in providing private wealth management products and services. Not all products and services are offered by all legal entities within BMO Private Wealth. Banking services are offered through Bank of Montreal. Investment management, wealth planning, tax planning, and philanthropy planning services are offered through BMO Nesbitt Burns Inc. and BMO Private Investment Counsel Inc. Estate, trust, and custodial services are offered through BMO Trust Company. Insurance services and products are offered through BMO Estate Insurance Advisory Services Inc., a wholly-owned subsidiary of BMO Nesbitt Burns Inc. BMO Private Wealth legal entities do not offer tax advice. If you are already a client of BMO Nesbitt Burns Inc., please contact your Investment Advisor for more information. BMO Nesbitt Burns Inc. is a Member – Canadian Investor Protection Fund and is a Member of Canadian Investment Regulatory Organization. BMO Trust Company and BMO Bank of Montreal are Members of CDIC. “BMO (M-bar roundel symbol)” is a registered trademark of Bank of Montreal, used under licence.
BMO Private Wealth provides this publication for informational purposes only and it is not and should not be construed as professional advice to any individual. This newsletter was produced by J. Hirasawa & Associates, an independent third party for the individual Investment Advisor noted. While every effort is made to ensure that the contents have been compiled or derived from sources believed to be reliable and contain information and opinions which are accurate and complete, the author does not accept responsibility or liability resulting from the information or content provided. The information contained in this publication is based on material believed to be reliable at the time of publication, but BMO Private Wealth cannot guarantee the information is accurate or complete. Individuals should contact their BMO representative for professional advice regarding their personal circumstances and/or financial position. The comments included in this publication are not intended to be a definitive analysis of tax applicability or trust and estates law. The comments are general in nature and professional advice regarding an individual’s particular tax position should be obtained in respect of any person’s specific circumstances.
BMO Private Wealth is a brand name for a business group consisting of Bank of Montreal and certain of its affiliates in providing private wealth management products and services. Not all products and services are offered by all legal entities within BMO Private Wealth. Banking services are offered through Bank of Montreal. Investment management, wealth planning, tax planning, philanthropy planning services are offered through BMO Nesbitt Burns Inc. and BMO Private Investment Counsel Inc. If you are already a client of BMO Nesbitt Burns Inc., please contact your Investment Advisor for more information. Estate, trust, and custodial services are offered through BMO Trust Company. BMO Private Wealth legal entities do not offer tax advice. BMO Trust Company and BMO Bank of Montreal are Members of CDIC.
® Registered trademark of Bank of Montreal, used under license.